Most workers who aren’t saving for retirement through their employers aren’t saving at all, the study found

New data suggests the average American worker has under $1,000 saved for retirement.

A report from the National Institute on Retirement Security found that the median savings for all employed adults between the ages of 21 and 64 were approximately $955. The study includes workers with 401(k) and other retirement savings plans, as well as the approximately 56 million workers who do not have access to employer-sponsored retirement plans.

Workers with retirement savings plans have a median balance of approximately $40,000 saved, according to the report. That figure is nowhere near the $1.5 million that Americans say they need to feel comfortable fully retiring.

top 81 comments

sorted by: hot top controversial new old
[–] 67 points 9 months ago (4 children)

Without universal healthcare, even if you save millions, it can all be wiped out with a single illness.

  • source
  • hideshow 4 child comments
  • [–] 39 points 9 months ago (1 child)

    I would say that is intended. Every day I'm more convinced that the US is the Billionaire playground where they can test out how to press the most money out of the population.

    With the big police state and enormous prison capacity ready to counter the eventual revolution.

    Perhaps they are suprised themselves that no one revolts as they suck more and more money out of the population and reveal more and more of the degenerate lifestyle of the elites.

    "They know that we f*ck and kill children and still don't revolt? What else do we need to do? We already take nearly all their money. Well, let's destroy the pension funds, perhaps that does the trick..."

  • source
  • hideshow 1 child comment
  • [–] 1 point 9 months ago

    We’re modern history’s largest slave empire. These rich are the descendants of actual slavers who were brutally violent. They treat this place like a plantation. It’s part of the culture of the American ruling class.

  • source
  • parent
  • [–] 87 points 9 months ago (13 children)

    I'm sure the situation is dire, but I'm not sure it communicates an accurate picture by lumping in 21 year olds with people who've been in the workforce for decades.

    21 yr olds who are just entering the workforce or are in college aren't expected to have much, if any, retirement savings at that stage in their lives.

    A better picture would be to break it down by age group. Still not a pretty picture, I'm sure.

  • source
  • hideshow 13 child comments
  • [+] 54 points 9 months ago (4 children)
  • [–] 6 points 9 months ago (2 children)

    I didn't start having meaningful savings until my mid 20s. When i bought a house paying off the mortgage became a priority over saving for retirement. I'll be better off paying less interest and reducing my expenses faster than I would be collecting interest on that money. In theory i could out perform my mortgage interest rate by trading stocks, but that is a lot riskier than paying off the mortgage.

  • source
  • parent
  • hideshow 2 child comments
  • [–] 4 points 9 months ago* (last edited 9 months ago) (1 child)

    Trading stocks is probably the worst investment strategy any normal person with a market-unrelated job and life responsibilities could pursue, with almost guaranteed losses in the long term. Good on you for identifying the high risk early in life- never forget it. That being said, there's very strong arguments for investing in stocks, but do it the boring way: large blended ETFs with a low expense ratio (like VTI, VTV, VOO, VXUS, or the Boglehead favorite: VT) or mutual funds. Don't "trade," buy and hold and try to forget you even have a brokerage account housing those blended, diversified funds. Try to use tax-advantaged vehicles as much as possible, like a Roth IRA or a Roth option in a 401k. Your mortgage APR is what? 4-7%? The market should definitely outperform that in the long term, and you can reduce your exposure to acute transient shifts even more by dollar cost averaging into your savings. I'm all for paying off debt as quickly as possible, for the psychological benefit, but there's also the rate race of your investment's probable APY vs your debt's APR.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 1 point 9 months ago

    I've been diversifying into some long term stock options in some of my savings accounts. I live quite frugally so I am able to still save a bit while paying a bit extra to my mortgage. So far I've done pretty good in the markets but my trading accounts aren't significant sums of money, when they do well I sometimes wish I invested more but when a stock is down bad I'm reminded why I keep those sums low.

    People underestimate what even $50 a month can do over time. Sure it might not be down payment money but it could be enough to build a safety net so you can try a new job or move somewhere else with a bit more behind you.

  • source
  • parent
  • [–] 3 points 9 months ago (1 child)

    This is still a shockingly low number. If you graduate with a bachelors and get a job our of college and contribute to a 401k, you should easily hit 1k saved within a year. If you didn't go to college and started working at 18, you'll be making less, but should still be able to save 1k by 22. Even shitty employers have retirement programs, it's just that most hourly workers won't take the time to sign up. There's only one way the median can be 1k, and that's because at least 40% have $0 saved and the whole system is completely broken for them.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 2 points 9 months ago

    This also seriously depends on the employer. One of the first things that gets slashed during benefit cuts is reitrement accounts, because they're an easy target and you're not "losing" the money.

  • source
  • parent
  • [–] 2 points 9 months ago (2 children)

    Wouldn't surprise me at all if the average retirement savings of those in their 50s is like $100,000

  • source
  • parent
  • hideshow 2 child comments
  • [–] 27 points 9 months ago

    well the solution is simple: deport brown people, ban trans people and give more money and tax cuts to corporations and billionaires. it'll all be over soon.

  • source
  • [–] 27 points 9 months ago (5 children)

    Fucking high rollers over there

    My retirement plan is to die at work, that way my family is taken care of. (who am I kidding, my work will try to weasel out of paying them if that happens)

  • source
  • hideshow 5 child comments
  • [–] 10 points 9 months ago (1 child)

    Learn from the French: burn shit before you get to the point of starvation.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 4 points 9 months ago*

    I mean, it took starvation for them to start burning shit the first time. But at least they learned from that, and haven’t let it get as bad since then.

    This is simply Americans’ first time experiencing the wrong side of the “let them eat cake” thing, so of course it’ll take a long time for America to start lighting things on fire.

  • source
  • parent
  • [–] 27 points 9 months ago (7 children)

    And you guys don't have a state pension either, right?

    You guys really need to get on with a revolution. Work until you die is kinda supposed to be something we are moving away from

  • source
  • hideshow 7 child comments
  • [–] 6 points 9 months ago (3 children)

    There's social security, which does give seniors enough to exist, but not much else.

  • source
  • parent
  • hideshow 3 child comments
  • [–] 12 points 9 months ago (2 children)

    Even SS is indexed by how much you earned as a wage-slave over your lifetime. If you've done something other than slaving for the Boss, or if your slaving has been for low pay, you get commensurately less in SS payments and the state will be happy to see you starve and freeze in old age.

  • source
  • parent
  • hideshow 2 child comments
  • [–] 7 points 9 months ago (1 child)

    That's unbelievably backwards. I had no idea America designed a system to perpetuate class divide into retirement.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 8 points 9 months ago*

    The actual formula is a bit complicated, but it boils down to a few key points:

    • you "pay into" the system at a fixed tax rate relative to your income, subject to a maximum cap after which you do not get taxed anymore.
    • in order to be eligible for benefits, you need to have 10 years of some amount of income. I think the threshold for that is extremely low, something like $8k/year.
    • when you retire, your income from your 35 highest earning years are sort-of-averaged together, subject to that cap I mentioned, to determine a monthly payment.
    • But, that value assumes you retire and take payments at 67. Take payments early, and you get less per month. Take payments later, and you get more.
    • Of course, none of this is guaranteed for future retirees. Current payments from workers go towards payments to current retirees, with the excess either saved for later or not due to the whims of the current administration. If there is ever not enough money to make payments, everyone likely takes that haircut.
  • source
  • parent
  • [–] 1 point 9 months ago

    we have social security which has its own tax structure taken out and you get relative to your pay in and most people will have to spend most of it on their health expenses from the retirement universal healthcare we have that has you pay 20% unless you sign up for a scam corpo thing that doesn't allow you to get proper healthcare so is cheaper. I worked for a company with european offices and when they went through the healthcare decuctible and out of pocket and savings accounts to pay for these things and such you could see some of the folks from over there were like. Wow. That is some shit.

  • source
  • parent
  • [–] 18 points 9 months ago (4 children)

    If your employer offers a 401(k) match, not trying to take advantage of that is one of the absolute dumbest financial moves you can make. Yes, I understand people sometimes can’t that’s why I said “try”.

    Another move is not investing early. The biggest boost to wealth in retirement is start saving early to take advantage of compounding interest.

  • source
  • hideshow 4 child comments
  • [–] 8 points 9 months ago (3 children)

    I'll upvote for the "try". Most people I know in tight spots need the money NOW. They are barely thinking 1 year ahead let alone 40.

  • source
  • parent
  • hideshow 3 child comments
  • [–] 5 points 9 months ago (2 children)

    I know people like that too. Those same people don't know how much they spend on anything, don't know where their money is going, and waste money on entertainment (subscriptions), drugs/alcohol, it other stupid shit. I wish they were more aware of their personal finance because I'd hate to see them when they're 55 trying to figure it out at the last minute.

  • source
  • parent
  • hideshow 2 child comments
  • [–] 3 points 9 months ago

    I'm pretty broke all the time, i absolutely know where all of it's going:

    1. bills
    2. groceries
    3. paying off debts from my young and dumb days.

    6 more months and i get to have a clothing and sundries budget again

    Honestly, comparing my finances to most of the people who have complained to me in person about living "paycheck to paycheck" the majority of people are trying to live middle class on working class incomes. I was guilty of it too, lifestyle creep happened.

    I shake my head every time I see people overspending on consumer bullshit while complaining about cost of living like their $20/day for energy drinks is reasonable.

  • source
  • parent
  • [–] 5 points 9 months ago

    I will say this. It annoys me when I see stuff like. Well these folks are stupid so they deserve it. I have definately known folks who can't do whats necessary to not be messed up in the us and its part of the reason we need real social democratic systems and safety nets. The us has this thing expecting everyone to be a jack of all trades for everything and being smart about every aspect of life. Everyone can't be a doctor, a lawyers, an accountant, a mechanic, and a all the various trades needed to properly handle property. I mean look whats expected with our taxes. Its nuts. Any society should run such that people can work a job and blow their paycheck every week and still do fine. Maybe not high on the hog but have food and shelter and healthcare and transportation and education if they need it. Because if we don't we are going to just create a bunch of problems that then get duct tape type solutions which is pretty much what you see in the us.

  • source
  • parent
  • [–] 22 points 9 months ago

    Garbage.

    Tell me the average of all people who have more than zero (and the number that represents), then tell me how many have zero.

    This number 955 doesn't mean shit.

  • source
  • [–] 11 points 9 months ago (3 children)

    I will be so happy eating cat food years from now knowing that I was more prepared than the average person.

  • source
  • hideshow 3 child comments
  • [–] 6 points 9 months ago (2 children)

    Smart move, acquiring the taste early. :(

  • source
  • parent
  • hideshow 2 child comments
  • [–] 5 points 9 months ago (1 child)

    I'm also one of those rare souls with a defined-benefit pension, so it will be Fancy Feast for me!

  • source
  • parent
  • hideshow 1 child comment
  • [–] 2 points 9 months ago*

    Well hello mr fancy pants! You know fancy feast is a canned brand right? You probably need to study your retirement savings carefully for this idea. Also the fancy feast cans shrank-- they are tiny now, so consider if you'll be opening more than one can per day.

  • source
  • parent
  • [–] 11 points 9 months ago (2 children)

    JFC this is depressing. Hopefully it forces some change though. I like that post about the French boyfriend asking why we don't burn shit. Hunger will make people burn shit.

  • source
  • hideshow 2 child comments
  • [–] 19 points 9 months ago* (last edited 9 months ago) (5 children)

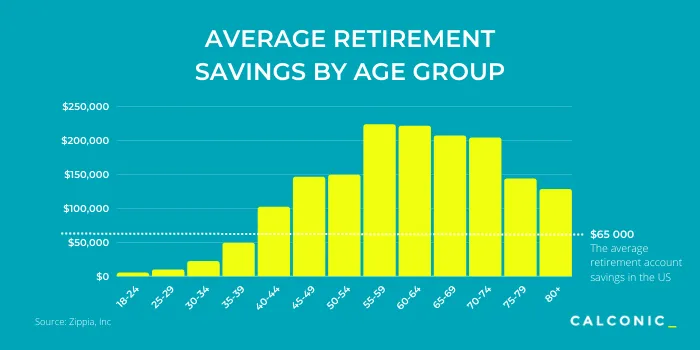
    This is a terrible stat. Taking the people who are entering the workforce and averaging them with people who have spent a lifetime working. Not only that, but that’s just “retirement” savings. How many 20 year olds have retirement accounts?

    The information would be far more realistic if it were grouped by decade of life.

    Edit: Here. This is a little better

    Savings

    Retirement savings
  • source
  • hideshow 5 child comments
  • [–] 13 points 9 months ago* (1 child)

    Still very bleak. Nobody is retiring comfortably on $60k, much less $10k.

    Might be worth factoring in SS, as that's the real practical retirement savings people rely upon.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 1 point 9 months ago

    The $60k represents remaining savings at age 80-89.

    Look at the 60-69 column for what people have around the time they start retiring. But not that those are means, not median figures, so are skewed by the US's vast levels of inequality.

  • source
  • parent
  • [–] 6 points 9 months ago*

    If by "average," they mean "mean," that's not a useful figure, since it's skewed by the disproportionate rewards going to the rich. And that's what that chart looks like. There's no way that the median for US people in their 60s is anywhere near $200k unless that involves some bullshit like imputing an NPV to their social security entitlement.

    OK, so I did some searching.

    Here's a more informative set of stats and charts: https://dqydj.com/retirement-savings-by-age/

    The age 60-64 median according to their more rigorous methodology is $10,400, not $200k.

  • source
  • parent
  • [–] 6 points 9 months ago*

    Median, not average, so much better at showing this situation than mean but it's still not great. I agree that it should be broken up, but the difficulty is how you define the grouping will have a significant impact on the results, especially in early and later years.

    I'd prefer median by age graphed by age. Average by any grouping will skew heavily if there is a lot of variance, and I absolutely expect there is in the US. A box-and-whisker plot could also be ideal here, but you still have the grouping problem.

  • source
  • parent
  • [–] 9 points 9 months ago (1 child)

    They have never wanted us to retire. They want us to work until we die.

  • source
  • hideshow 1 child comment
  • [–] 1 point 9 months ago

    workers will not be allowed to work until they die unless its a really menial job. Every normal mundane mistake you make as an older worker, your bosses look at you trying to decide if you are too old to do the job.

  • source
  • parent
  • [–] 7 points 9 months ago* (2 children)

    Our lavish lifestyles include paying for food, shelter, healthcare, power and water and it keeps costing more and more but there’s record shareholder profits!!!! Yeah! You should be happy that the economy is great for pedofiles who rape children and possibly(checks notes) eat babies on yachts. Cool! they’re openly using all our tax dollars with the goal of making us working people obsolete while mass surveilling us and killing dissenters in the streets. Awesome

  • source
  • hideshow 2 child comments
  • [–] 19 points 9 months ago (8 children)

    Lots of people saying it's a skill issue that people aren't saving more of their earnings. The problem is much deeper: it doesn't make sense for the majority of Americans to save their money. This is the rational outcome of a political and economic system that does not offer hope, only cynicism.

  • source
  • hideshow 8 child comments
  • [–] 8 points 9 months ago (2 children)

    I had several 401ks, I cashed them out fairly quickly because an emergency would come along and it was the only thing between me and homelessness, or not receiving medical care.

    Now I have a 403(b) because I work for higher ed, and I am forbidden to cash it out, but I've taken a loan against it and paid off my credit cards, and am paying myself interest now.

    So now I have my CCs freed up for the next time I have an emergency, which will be checks watch

  • source
  • parent
  • hideshow 2 child comments
  • [–] 2 points 9 months ago

    I had almost completely strip-mined my 401k and post-tax investments by the time I was 56 due to a family member's mental-health crisis and the downstream impact of that (it was worth it: the family member in question is now stable and thriving). I'm now 70 and should be able to retire next year if some other emegency doesn't bite us on the ass before then. It took 14 years to rebuild, and that was with my wife and me both bringing in professional salaries and having additional investments.

  • source
  • parent
  • [–] 1 point 9 months ago

    I feel the "checking watch for next emergency"

    I'm just about done paying off my last emergency so I'm right on time for the next big one. Fate seems to wait until I'm spitting distance from paying it off to taunt me or some shit.

    The last time I was literally 1 month from having it paid off before BOOM $10k medical emergency and to not become homeless due to said medical emergency combined with being on FMLA for 12 weeks minus a day.

    It don't like like a lot to some but for me it's been hell.

  • source
  • parent
  • [–] 7 points 9 months ago (1 child)

    If it was a handful of people, it could MAYBE be a skill issue. But when it's most people, it's a systemic issue.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 3 points 9 months ago

    I had an argument about that with the college when I failed ochem. 2/3 of the students failed ochem that year. My argument was basically they made the tests too hard just to weed people out because I aced the lab class and always had As on my papers. Papers where you performed real world calculations not insane ones. There reply was basically yeah its a weed out class take it again or switch majors but we'll let you keep your scholarship... for now. Kept major, switched schools a year later then switched majors.

  • source
  • parent
  • [–] 3 points 9 months ago (2 children)

    I’m not from USA so I don’t know what rates of interest your banks offer, but most here offer less than 4%, so there doesn’t seem much point for a few hundred quid.

  • source
  • parent
  • hideshow 2 child comments
  • [–] 3 points 9 months ago* (last edited 9 months ago)

    In the retirement account front, just checked and for the past year it hit 19%, over the last 10 years, it's been 15% a year. Generally those are biased toward stock and move to more conservative close to retirement. I think that's generally the balance being considered, at least if you have any retirement account, it's probably larger than any other account in short order.

    For "savings" account recently 4% has been available, but less so now as the central bank turns down interest rates to favor borrowers again. But I don't think they are limiting to strict savings accounts here. I think money put into an index fund or bonds or CDs would absolutely count.

  • source
  • parent
  • [–] 6 points 9 months ago

    I sure wish I had 955$ saved!

  • source
  • [–] 11 points 9 months ago

    Soon there will be a critical mass of people who have nothing left to lose. Thats why the Democrats and Republicans need the military in the streets. Their wealthy benefactors cannot allow anything like the New Deal to happen again.

  • source
  • [–] 5 points 9 months ago (1 child)

    There's gonna be a rash of people committing crimes in their 70s and 80s just to have a place to live and three meals a day.

  • source
  • hideshow 1 child comment
  • [–] 5 points 9 months ago (3 children)

    Very misleading stats. What’s the breakdown by age group? A 21-year old with <$1000 in savings is very different from a 64-year old. Talking about the “average worker” across that wide of an age range is totally meaningless. What’s the median age?

  • source
  • hideshow 3 child comments
  • [–] 1 point 9 months ago (2 children)

    I mean 21 to 64 of all employed adults. I doubt there are so many 21 year olds that they are tipping the scales to under a grand on their own. Theoretically the mean should be especially relevant to the middle of the spectrum. I can say im later than that and drawing down savings over the last year as I have been out of work. I keep saying I know there are gonna be these articles about how gen X did not save enough for retirement and its going to be like sigh. I tried as much as I could when I could.

  • source
  • parent
  • hideshow 2 child comments
  • [–] 1 point 9 months ago (1 child)

    Well I think employed 21-year olds are a lot less likely to have any savings at all (mostly student loans) and also more likely to be working in a job with no retirement plan (working at Subway or Starbucks). Combining their situation to a 64-year old in an office job or a skilled trade is still pretty misleading.

    Yes, it’s a huge problem that young people have all this student debt and lack of savings and high living expenses. But we’re not going to be able to analyze that by lumping all their numbers together with older people. If we want to make comparisons we need separate numbers.

  • source
  • parent
  • hideshow 1 child comment
  • [–] 2 points 9 months ago*

    yeah I mean even if you take 0 for them that would bring down an equivalent number of folks with 2k and we know the opposite situation occurs with c suite folks and such having real high numbers. Even then if it is 20somethings it still highlights an issue we have now that was not the case 50 years ago. 20somethings can't save at all. 30somethings if they are lucky can start to save but kinda want a house someday so wants to save some in a regular way (which is also smart. its very important to have a short term savings no matter the tax advantage of retirement savings). It they are lucky maybe they can swing the mortgage in their 40's but that puts a damper on retirement savings as well given mortage payments. So like 50's you can finally really start socking it away for your impending retirement. again if you are lucky.

  • source
  • parent
  • [–] 8 points 9 months ago (2 children)

    Social Security was the single greatest transfer of wealth from employers to employees in US history

  • source
  • hideshow 2 child comments
  • [–] 4 points 9 months ago

    My retirement plan is my benelli.

  • source
  • [–] 4 points 9 months ago

    Don't tell the ultra wealthy! They'll start the ploy to "recover" what they're missing out on. Usually by funding systems to convince voters to elect someone who'll get it for them the fastest

  • source
  • load more comments
    view more: next ›